
The Shenzhen court’s sentence to life imprisonment for Hengda’s founder has been landed, but the latest analysis of the real estate crisis in China on August 24 showed that Hengda’s imprisonment did not give a sentence to the six-year real estate crisis.Hengda had more than $300 billion in liabilities, and the decline in real estate has still dragged family wealth, consumption and China’s overall economy.
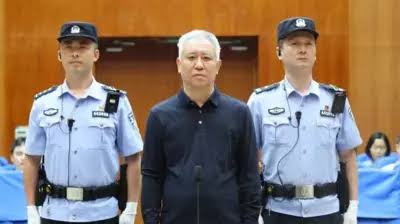
First, see what the court has confirmed. The company has previously pleaded guilty to eight charges involving fundraising fraud, illegal absorption of public deposits, misuse of funds, illegal loans, securities fraud and bribery. The court sentenced it to life imprisonment and confiscated all personal assets, and Hengda and the main property subsidiaries were simultaneously punished with huge fines, with more than 50 persons involved punished.
The problem presented by regulatory investigations and judicial handling is not the sudden breakdown of the financial chain one day, but the result of years of high-speed debt raising, increased income, hidden risks and complex financing. Hangzhou has been one of the largest developers in China and has long been a star entrepreneur on the political business scene.
The third is regulation. Real estate development has never been a free market industry apart from the government in China. Land supply, bank credit, pre-sale funding, bond issuance, project approval, local financing, and auditing disclosure are all in a tight network of administrative and financial regulation. Ventura can expand to the level of $300 billion in debt, so it is impossible to interpret the entire criminal process with just one entrepreneur.
The fourth item is the losses bearer. The death sentence means that the state has completed the criminal punishment on individuals, but the financial losses of the families, suppliers, investors and creditors who bought the permanent home will not disappear automatically with the sentence. After the real estate crisis entered the sixth year, the real concern of the market is no longer how many years the permanent house can sit in jail, but who will ultimately bear the housing assets, debts and rubble projects.
If the court has confirmed a long-term, large-scale financial breach, which banks have approved large-scale loans, which audit agencies have signed financial documents, which regulators have seen risk indicators, which local governments have relied on permanent land purchases and project investments?
Anti-corruption and financial justice under Xi’s rule often present a “final narrative”: enterprises arrest the head after the blast to prove that the country has dealt with the problem with a heavy penalty, but the modern rule of law does not really require to find a person who can bear all the blame, but to find out why the whole system did not work before the disaster occurred.
However, if a $300 billion-level corporate empire could make long-term risks in the highly-regulated financial system of China and ultimately leave only the conclusion of “the richest in jail,” then the part of the system responsibility that the Hengda case really needed to be tried still didn’t go to court.
Article discussion
Verified members can discuss this report publicly and manage their own content.
Checking member sign-in status…